

- ಕನ್ನಡದಲ್ಲಿ ಪ್ರಮುಖ ಅಂಶಗಳು
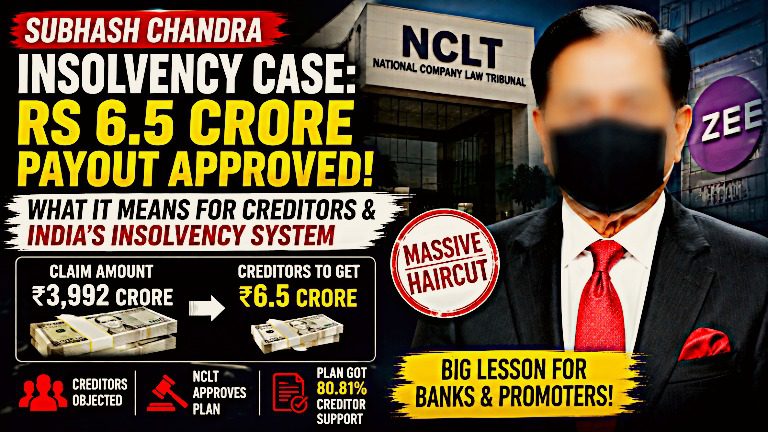
* ₹3,992 ಕೋಟಿ ಕ್ಲೇಮ್ಗೆ ಕೇವಲ ₹6.5 ಕೋಟಿ ಪಾವತಿ: NCLT ಅನುಮೋದಿಸಿದ repayment plan ಪ್ರಕಾರ, ವೈಯಕ್ತಿಕ ಗ್ಯಾರಂಟರ್ ಆಗಿರುವ ಸುಭಾಷ್ ಚಂದ್ರ ವಿರುದ್ಧದ ₹3,992 ಕೋಟಿ ಕ್ಲೇಮ್ಗೆ ಕೇವಲ ₹6.5 ಕೋಟಿ ಪಾವತಿಯಾಗಲಿದೆ.
* ಇದು ದೊಡ್ಡ “ಹೇರ್ಕಟ್”: ಸಾಲದಾತರು ಕೇಳಿರುವ ಮೊತ್ತ ಮತ್ತು ವಾಸ್ತವವಾಗಿ ಸಿಗಲಿರುವ ಮೊತ್ತದ ನಡುವೆ ಭಾರೀ ವ್ಯತ್ಯಾಸವಿದೆ. ಇದರಿಂದ ಭಾರತದ personal insolvency ವ್ಯವಸ್ಥೆಯ ಕುರಿತು ಪ್ರಶ್ನೆಗಳು ಎದ್ದಿವೆ.
* ಸುಭಾಷ್ ಚಂದ್ರ ಅವರ ಸ್ಪಷ್ಟನೆ: ಅವರ ಕಚೇರಿ ಹೇಳುವ ಪ್ರಕಾರ, ಅವರು ಸ್ವತಃ ಸಾಲ ಪಡೆದವರಲ್ಲ; Essel Groupಗೆ ಸಂಬಂಧಿಸಿದ ಕಂಪನಿಗಳ ಸಾಲಗಳಿಗೆ ಅವರು personal guarantor ಆಗಿದ್ದರು.
* ₹620 ಕೋಟಿ ಕ್ಲೇಮ್ ಈಗಾಗಲೇ ಸೆಟಲ್ ಆಗಿದೆ: ಅವರ ಕಚೇರಿ ನೀಡಿದ ಮಾಹಿತಿಯ ಪ್ರಕಾರ, ₹620 ಕೋಟಿ ಮೊತ್ತದ ಕ್ಲೇಮ್ ಇತ್ಯರ್ಥಗೊಂಡಿದ್ದು, ಮತ್ತಷ್ಟು ₹1,063 ಕೋಟಿ ಪಾವತಿಯನ್ನು borrower entities ನೀಡಲು ಮುಂದಾಗಿವೆ.
* ₹43,000 ಕೋಟಿ ಮರುಪಾವತಿ: ಚಂದ್ರ ಅವರ ಕಚೇರಿ ಪ್ರಕಾರ, ಅವರಿಗೆ ಸಂಬಂಧಿಸಿದ borrowing entities ಇದುವರೆಗೆ ಸುಮಾರು ₹43,000 ಕೋಟಿ ಮರುಪಾವತಿ ಮಾಡಿವೆ.
ಅವರ ವೈಯಕ್ತಿಕ ಆಸ್ತಿ ಬಗ್ಗೆ ಹೇಳಿಕೆ: 2016ರಲ್ಲಿ ತಮ್ಮ ಒಟ್ಟು ಆಸ್ತಿ ₹39.08 ಕೋಟಿ ಎಂದು ಘೋಷಿಸಿದ್ದಾಗಿ ಹಾಗೂ 2024ರಲ್ಲಿ ಅದು ₹31.79 ಕೋಟಿಗೆ ಇಳಿದಿದೆ ಎಂದು ಅವರ ಕಚೇರಿ ತಿಳಿಸಿದೆ.
* NCLTಯ ಮಹತ್ವದ ನಿರ್ಧಾರ: ಇಬ್ಬರು ಸದಸ್ಯರ NCLT ಪೀಠದಲ್ಲಿ ಭಿನ್ನಾಭಿಪ್ರಾಯ ಉಂಟಾದ ನಂತರ ಮೂರನೇ ಸದಸ್ಯರ ಅಭಿಪ್ರಾಯದ ಮೂಲಕ repayment planಗೆ ಅನುಮೋದನೆ ದೊರೆಯಿತು.
* ಸಾಲದಾತರಿಗೆ ಸುಮಾರು 80.81% ಬೆಂಬಲ: repayment plan ಅಗತ್ಯವಿರುವ creditor voting support ಪಡೆದಿತ್ತು. NCLT ಅಂತಿಮವಾಗಿ ಯೋಜನೆಯನ್ನು ಅನುಮೋದಿಸಿತು.
ಸಾಲದಾತರ ಆಕ್ಷೇಪಣೆ: ಅತ್ಯಂತ ಕಡಿಮೆ recovery, ಆಸ್ತಿಗಳ ಮೌಲ್ಯಮಾಪನ ಮತ್ತು forensic investigation ಅಗತ್ಯವಿತ್ತೇ ಎಂಬ ಬಗ್ಗೆ creditors ಪ್ರಶ್ನೆ ಎತ್ತಿದ್ದರು.
* ಬ್ಯಾಂಕ್ಗಳಿಗೆ ಪ್ರಮುಖ ಪಾಠ: ದೊಡ್ಡ ಮೊತ್ತದ personal guarantee ಇದ್ದರೂ, guarantor ಬಳಿ ವಾಸ್ತವವಾಗಿ ವಸೂಲಿ ಮಾಡಬಹುದಾದ ಆಸ್ತಿ ಇಲ್ಲದಿದ್ದರೆ ಬ್ಯಾಂಕ್ಗಳಿಗೆ ಸಂಪೂರ್ಣ ಹಣ ಮರಳಿ ಪಡೆಯುವುದು ಕಷ್ಟವಾಗಬಹುದು.
₹3,992 Crore Claim, Just ₹6.5 Crore Recovery: What Subhash Chandra’s NCLT Order Means
A recent order in the personal insolvency proceedings involving Zee Group founder Subhash Chandra has brought renewed attention to one of the biggest questions facing India’s insolvency framework: how much can creditors realistically recover when a promoter’s personal guarantee is enforced?
The National Company Law Tribunal (NCLT) has approved a repayment plan under which creditors are set to receive ₹6.5 crore, despite claims against Subhash Chandra of around ₹3,992 crore, according to the information provided in the case report.
The huge difference between the amount claimed and the amount proposed for repayment has triggered questions about creditor recovery, personal guarantees, asset disclosure and the effectiveness of India’s personal insolvency mechanism.
The case is particularly significant because it illustrates an important distinction in financial disputes: the amount a creditor is owed is not necessarily the amount that can ultimately be recovered from a guarantor.
₹3,992 crore claim versus ₹6.5 crore repayment
The most striking figure in the case is the enormous gap between the claim and the approved repayment amount.
According to the report, the claim against Chandra as a personal guarantor in the proceedings was stated by the objectors to be approximately ₹3,992 crore.
Against this amount, the approved repayment plan provides for only ₹6.5 crore.
That means the proposed repayment represents only a tiny fraction of the amount claimed.
The outcome has consequently been described as an exceptionally large haircut for creditors.
However, the case needs to be understood in the context of personal insolvency proceedings, rather than being treated simply as a dispute over the entire debt of the wider Essel Group.
Why was Subhash Chandra personally involved?
The proceedings relate to personal guarantees provided by Subhash Chandra for borrowings of Essel Group-linked companies.
A personal guarantee is a commitment by an individual to meet obligations if the borrower fails to repay, subject to the applicable legal process.
This means Chandra’s involvement in the insolvency proceedings does not necessarily mean that he personally borrowed the entire amount claimed.
His office has specifically argued that he was a personal guarantor rather than the borrower.
In a statement cited in the report, Chandra’s office said the total claim against him as a personal guarantor was ₹3,992 crore and not ₹22,000 crore.
The statement also said that ₹620 crore of the claim had been settled and that borrower entities had offered another ₹1,063 crore.
According to the statement, borrowing entities for which Chandra had provided personal guarantees had already repaid ₹43,000 crore and had assured that other outstanding amounts would also be settled.
These claims form part of Chandra’s position in the dispute and should be distinguished from the tribunal’s assessment of the repayment plan.
The big question: Why only ₹6.5 crore?
The answer largely comes down to the assets available within the personal insolvency process.
Chandra’s office stated that his declared assets were worth approximately ₹39.08 crore in 2016, based on a declaration made to Parliament.
It further said that his personal net worth had declined to approximately ₹31.79 crore in 2024, including a residential property valued at around ₹25 crore.
The argument presented by Chandra’s office was that the repayment plan was based on what he could realistically pay from his available personal assets.
In simple terms, a creditor can have a very large claim against a guarantor, but recovery ultimately depends on the assets that are legally available for recovery and the outcome of the insolvency process.
This is one of the central lessons emerging from the case.
NCLT had to resolve a split decision
The August 25 NCLT order was not the result of a straightforward unanimous decision.
The report states that a two-member NCLT bench had previously delivered a split verdict on the repayment plan.
Because the members disagreed, Nilesh Sharma, judicial member of the NCLT, acted as the third member to resolve the disagreement.
The third member ultimately supported approval of the repayment plan.
The decision means the plan could move forward despite objections raised by creditors.
Why did creditors object?
Creditors understandably questioned the extremely low recovery.
Their objections reportedly included concerns about:
The very small amount being offered compared with the claims
The financial position of the debtor
Whether all assets had been adequately examined
Whether a forensic investigation was necessary
Whether creditors could obtain a better recovery through another route
The central concern was straightforward:
Could more money have been recovered if the debtor’s financial affairs and assets had been examined more extensively?
The creditors’ position highlights the tension that can arise within insolvency proceedings.
Creditors want to maximise recovery, while the insolvency framework seeks to determine the best legally and commercially viable outcome based on the debtor’s circumstances.
Why did the tribunal approve the plan?
According to the report, the tribunal took a pragmatic approach.
The NCLT concluded that the approved repayment plan could provide a better outcome than pushing the matter into bankruptcy.
That is a crucial part of understanding the decision.
The question was not simply whether ₹6.5 crore looked small compared with a ₹3,992 crore claim.
Instead, the tribunal had to consider whether the alternative could realistically generate a better recovery.
If bankruptcy or another process would result in an even smaller recovery, accepting ₹6.5 crore could potentially be considered the better outcome.
This is an important principle in insolvency proceedings: a large claim does not automatically translate into a large recovery.
Creditors’ commercial decision also mattered
Another important aspect of the order was the role of creditors.
The repayment plan reportedly received around 80.81% of the voting share.
Under the insolvency framework, creditors have an important commercial role in evaluating and voting on repayment proposals.
Once the required majority approves a plan and the tribunal sanctions it, individual dissenting creditors generally cannot simply abandon the process and demand an entirely different settlement.
The tribunal also emphasised the importance of the commercial decision taken by creditors.
This means the NCLT does not ordinarily substitute its own commercial judgment for that of creditors when the plan has been approved according to the applicable insolvency process.
Why the case matters for India’s insolvency system
The Subhash Chandra case goes beyond one businessman or one corporate group.
It highlights a structural issue that banks and financial institutions face when lending to promoter-backed companies.
A personal guarantee can provide additional security to a lender.
But a guarantee is not the same as cash or immediately recoverable assets.
Its ultimate value depends on:
The guarantor’s legally available assets
The enforceability of the guarantee
The insolvency process
Existing liabilities
Asset valuation
The tribunal’s findings
The repayment plan approved by creditors
This means banks need to look beyond the headline net worth or business reputation of a promoter when evaluating guarantees.
A warning for lenders
The case could serve as a reminder to lenders that promoter guarantees need careful assessment.
A promoter may control or have historically been associated with companies worth thousands of crores, but that does not necessarily mean the promoter personally possesses assets worth the same amount.
This distinction becomes particularly important when corporate borrowers default and lenders attempt to enforce personal guarantees.
The value of a guarantee depends on the guarantor’s actual financial capacity and the assets that can legally be brought into the recovery process.
For banks, therefore, the key question is not merely:
“Does the promoter have a personal guarantee?”
It is also:
“What is the realistic recoverable value of that guarantee?”
The ₹43,000 crore repayment claim
Chandra’s office has also presented a broader argument concerning repayments by the borrowing entities.
According to the statement cited in the report, companies for which Chandra had provided personal guarantees had repaid approximately ₹43,000 crore.
The statement also claimed that these borrowing entities had assured settlement of other amounts that may remain outstanding.
These figures are part of Chandra’s response and should not be interpreted as meaning that the NCLT has declared all claims against the wider group fully settled.
The personal insolvency proceedings concern Chandra’s liability arising from guarantees and must be distinguished from separate corporate insolvency and regulatory proceedings.
Why ₹22,000 crore and ₹3,992 crore figures are different
One of the potentially confusing elements of the case is the appearance of different debt figures.
Chandra’s office has specifically disputed the use of a ₹22,000 crore figure in relation to his personal insolvency proceedings.
It stated that the claim against him as a personal guarantor in these proceedings was ₹3,992 crore.
This distinction matters because corporate-level debt and personal liability arising from guarantees are not necessarily identical.
A company can have very large borrowings, while a particular individual’s liability under personal guarantees may be calculated differently.
Therefore, readers should avoid automatically treating the wider Essel Group’s financial obligations as the same as Chandra’s personal insolvency claim.
Does the order wipe out all other legal proceedings?
No.
The NCLT order concerning the repayment plan should not be interpreted as ending every legal or regulatory matter involving Subhash Chandra, Zee Entertainment or other Essel Group entities.
The report specifically distinguishes the personal insolvency case from separate regulatory proceedings involving Zee Entertainment Enterprises and its executives.
Similarly, corporate insolvency proceedings involving companies associated with the Essel Group are separate matters.
The approval of the personal repayment plan therefore has a specific legal scope.
What does the case mean for creditors?
For creditors, the case demonstrates the difference between claim value and recovery value.
A lender could theoretically have a claim worth thousands of crores but recover only a fraction if the available assets are insufficient.
That can be frustrating from the creditor’s perspective, particularly where questions remain about the debtor’s financial affairs or asset valuation.
At the same time, insolvency proceedings are designed to establish a structured mechanism for dealing with financial distress rather than allowing creditors to independently pursue unlimited recovery outside the framework.
The tribunal’s decision reflects this balance between maximising recovery and concluding the insolvency process.
What does it mean for borrowers and promoters?
For promoters, the case is another reminder that personal guarantees can have significant consequences.
Giving a personal guarantee for corporate borrowing can expose an individual’s personal assets to legal recovery processes if the underlying borrower defaults.
A promoter cannot necessarily assume that corporate borrowing will remain entirely separate from personal financial exposure when personal guarantees have been provided.
The case also demonstrates why the financial position of a guarantor can become a central issue during insolvency proceedings.
What does it mean for India’s IBC mechanism?
India’s Insolvency and Bankruptcy Code was designed to create a structured process for resolving insolvency and improving creditor recovery.
The Subhash Chandra case illustrates both the strengths and limitations of that framework.
On one hand, the process provided a formal mechanism through which creditors could vote on a repayment proposal and the NCLT could adjudicate objections.
On the other hand, the enormous gap between the claim amount and proposed recovery raises broader questions about how effectively personal insolvency proceedings can convert large claims into actual recoveries.
The case therefore becomes an important example for discussions around:
Creditor recovery
Personal insolvency
Promoter guarantees
Asset disclosure
Forensic examination
Commercial decisions by creditors
NCLT oversight
The effectiveness of India’s insolvency mechanism
The bigger lesson: Debt is not the same as recoverable money
Perhaps the clearest lesson from the case is that a ₹3,992 crore claim does not mean ₹3,992 crore is available for repayment.
The final recovery depends on what assets exist, what can legally be recovered, what creditors approve and what the tribunal ultimately sanctions.
That is why the ₹6.5 crore figure has attracted so much attention.
It represents a dramatic difference between the size of the claim and the amount expected to be recovered under the approved plan.
For the banking sector, it is a reminder that the strength of a guarantee ultimately depends on its enforceability and the financial resources supporting it.
For the insolvency system, it is another test of whether a structured settlement can deliver the best realistically available outcome.
And for creditors, it demonstrates a difficult reality: winning a claim and recovering the money are two very different things.
FAQs
- What is the Subhash Chandra insolvency case about?
The case concerns personal insolvency proceedings against Zee Group founder Subhash Chandra arising from personal guarantees provided for borrowings of Essel Group-linked companies.
- How much is the claim against Subhash Chandra?
According to the information provided in the report, the claim against Chandra as a personal guarantor in the proceedings was stated to be around ₹3,992 crore. His office disputed references to a ₹22,000 crore personal claim.
- How much will creditors receive under the approved plan?
The approved repayment plan provides for ₹6.5 crore to creditors, according to the report.
- Why is the ₹6.5 crore amount controversial?
The amount is extremely small compared with the ₹3,992 crore claim, leading creditors to question whether a greater recovery could have been achieved.
- Why did the NCLT approve the repayment plan?
The tribunal concluded that the repayment plan could provide a better outcome than pushing the matter into bankruptcy, according to the report.
- Did creditors approve the plan?
The repayment plan reportedly received approximately 80.81% of the voting share.
- What is a personal guarantee?
A personal guarantee is an individual’s commitment to meet a borrower’s obligations if the borrower defaults, subject to the applicable legal process.
- Does the NCLT order mean Subhash Chandra has no other legal issues?
No. The personal insolvency proceedings are separate from other corporate, regulatory and legal proceedings involving Zee Entertainment and Essel Group-linked entities.
- Why is the case important for banks?
The case highlights that a large personal guarantee does not automatically guarantee a large recovery. Banks need to assess the guarantor’s actual assets and financial capacity.
- Does a large corporate debt automatically become the promoter’s personal debt?
Not necessarily. Personal liability can arise from specific guarantees and the applicable legal process. Corporate debt and personal guarantee liability should not automatically be treated as identical.
Disclaimer
Disclaimer: This article is based on the source material provided and the facts and statements reported therein. References to claims, repayment amounts, creditor objections and statements attributed to Subhash Chandra’s office are presented as reported and should not be interpreted as independent findings unless specifically stated. The ₹6.5 crore repayment plan, ₹3,992 crore claim and other figures may be subject to legal proceedings, clarification or further developments. This article is for informational and educational purposes only and should not be considered legal, financial or investment advice.
Do Follow For More Info @ http://roydailyupdate.in
Do WhatsApp @ https://chat.whatsapp.com/K5POJK9KbpN8egjjOCaOw6
About the Author
Ravi is a digital content creator and blogger at RoyDailyUpdate, covering business, stock markets, technology, jobs, breaking news and major developments in India and around the world. His articles focus on explaining complex developments in a simple, reader-friendly format while highlighting the key facts, numbers and context that matter to readers.